Introduction
A small business is not only about providing your products or services. You have to take care of managing your cash flow, bookkeeping, controlling your expenses, filing taxes, and planning your development, at the same time taking care of your clients, suppliers, and employees.
From tradesmen in Basildon to café owners in Southend-on-Sea and consultants in Chelmsford and even landlords in Colchester, Essex businesses are diverse. Yet they all share the need to have an idea about their finances. This guide focuses on important habits you should have and provides some practical tips that you can apply right away, and also discusses Making Tax Digital for Income Tax, which is coming soon.
Know your Cash Flow
Cash flow refers to the movement of money into and out of your business. A business with a lot of sales could be facing financial difficulties if its customers do not pay until later and it has to make payments earlier.
For example, a tradesperson in Chelmsford makes an invoice worth £4,800 on the 1st and pays after 45 days. However, materials, fuel, and insurance payments need to be made in the meantime. There is plenty of work but no cash. The problem can be solved through the following three small adjustments. Invoice immediately upon completion of work, reduce payment period to 14 days, and charge a deposit for large orders.
A cash flow projection helps predict future income and expenses. It can be updated regularly as invoices get paid and costs vary. Steps to consider include the following.
- Record expected customer payments and due dates
- List regular costs such as wages, rent, utilities and supplier payments
- Chase overdue invoices promptly
- Set money aside for upcoming tax bills
- Set aside funds for emergencies
Revenues and cash flows are two different terms. Monitoring cash flow will tell you when you can buy additional equipment or expand your workforce.
The rolling 13-week cash flow forecast is an easy-to-manage approach for most small companies. It involves listing all incoming payments and outgoing bills on a weekly basis, and adding the initial bank balance to establish the lowest point in the forecast. If the lowest point comes in week six, you have enough time to deal with it by contacting the customer, postponing any unnecessary expenditure, or getting a short-term overdraft before things get tough. Late paying customers should also be given an opportunity to respond. Send a polite reminder a few days before the date and another one on the actual date, noting that statutory interest applies to late commercial payments. Consistency is usually more productive than threatening.
Maintain Precise and Current Records
Accurate records will help you analyze performance, prepare accounts, and file taxes. Recording all purchases, payments, cash receipts, salaries and banking activity regularly is much simpler than compiling all this data at once near the deadline.
Cloud accounting software allows for invoicing, bank reconciliations and reports. Select one that suits your needs and not a system with many other unnecessary features. Using a separate bank account for your business will also keep all the income and expenses organized.
Your weekly routine should be completed within one hour. Scan or photograph all receipts immediately as you get them, reconcile your bank feed to your accounting system, send invoices that have not been sent yet and list all outstanding clients.
Most of the Essex business owners realize that bookkeeping takes much longer than anticipated. That is why keeping it current every week is the simplest approach to save time. Collaboration with professional accountants in Essex will assist businesses, freelancers, landlords and limited companies to keep their record keeping in order.
Keep your proof of the transaction in such a way that another person could understand it, since your accountant or HMRC will need to trace your transactions. Name your documents according to the date and name of the supplier, organize everything in one folder digitally or even inside your accounting system and do not leave receipts in your vehicle, coat pocket or personal email.
It should be noted that business records will normally have to be retained for a number of years, and keeping your archive organised will make your work easier in the future. Special attention should be paid to mileage since it is essential to all Essex businesses and independent contractors, whose working hours require moving from one place to another. Record every trip together with the date, destination and purpose at the very moment, and not at the year-end period based on estimation.
Create a Realistic Budget
The budget will allow seeing how much money is available for operation and where to spend it. You should start with previous records or reasonable estimates and supplier quotations if you are setting up a new business. Classify all expenses into categories: premises, personnel, inventory, promotion, insurance, computer software and travel, and distinguish fixed from variable expenses.
For example, a retailer from Southend-on-Sea planning for the busy summer season might require additional inventory and employees. It is important to know in advance what amount can be allocated without compromising other commitments.
Review it every month and compare performance against your predictions. If income does not meet expectations, find places where you can cut costs without impacting on service delivery. If income exceeds expectations, determine how much to reinvest, reserve or pay for future commitments.
Construct your budget in three tiers. Begin with necessities such as rent, salaries, insurance premiums, loan payments, and taxes. Consider the expenses necessary for keeping your business competitive, like marketing, technology and training. Finally, include those expenses that you can delay if required. When you run into financial difficulties, you will know which to cut off first. Another tip is to keep a separate budget for expenses that occur once per year, including insurance premiums, car servicing and subscription fees. Divide these expenses by twelve months to ensure the costs are distributed evenly throughout the year. This little trick will prevent large expenses from coming up in the month where you need money most.
Watch Spending and Save Money
Little charges pile up. Unneeded software, subscription services, shipping charges and rising supplier prices chip away at profits. Consider negotiating different payment terms or comparing supplier prices, but don’t forget the lowest cost isn’t necessarily the most dependable choice.
Maintain documentation on all eligible business expenses. Not everything purchased while performing business qualifies for tax deductions; therefore, verify eligibility of an expense if uncertain.
Quarterly expense analysis requires about an hour and frequently more than makes itself worth the time invested. Obtain the past three months of bank records and highlight all recurring expenses. Then question whether each expense remains worthwhile, fairly priced and necessary. Insurance, broadband internet, mobile phone agreements, credit card transaction fees and petrol are typical categories from which modest savings result. Seek at least two quotations before renewal of a large contract, and employ another quotation when negotiating with the current supplier. Additionally, investigate payment methods. Discounts for early payments or annual payments may save money, if your budget can afford the initial outlay.
Be Tax Savvy
Financial management needs to take into consideration the tax implications of income from time to time, rather than doing everything at the last minute. Self-employed individuals and private landlords need to make use of Self Assessment, while limited companies need to file corporation tax returns.
Make sure you keep track of deadlines and put in reminders well in advance. Just remember that not everything you earn is disposable income because some of it needs to pay for taxes. Many owners open a separate savings account and move a set share of every payment into it, with the percentage agreed with their accountant based on expected profit. When the bill arrives, the money is already there.
Two dates catch many Essex sole traders and landlords by surprise. It must be remembered that Self Assessment payments on account, which represent advance payments for the next year’s bill, which are generally due on 31st January and 31st July, will have a double effect in the first year.
Limited companies’ directors must bear in mind that Corporation Tax, Payroll Tax, and VAT have their own schedules for submission. If you are approaching the VAT threshold limit, remember to track your total twelve months turnover on a monthly basis as opposed to an annual basis to avoid missing the threshold limit.
Prepare for Making Tax Digital for Income Tax
The most important thing for many Essex sole traders and landlords is Making Tax Digital (MTD) for Income Tax. This replaces the annual process of self-assessment with a system of keeping digital records and providing HMRC with updates. There are three tasks you will need to complete.
- Keep income and expenses for businesses and properties in MTD-compliant software
- Provide HMRC with an update quarterly
- Submit a final declaration at the end of the tax year
It is being phased in based on qualifying income, which is your gross self-employment and property income combined, before expenses.
These rules trap more people than you might think. Someone who is a landlord in Colchester or Brentwood with a few properties, or someone commuting to Chelmsford with a part-time business, may fall foul once additional rental or part-time income is added to their own self-employment income. To prepare yourself, follow these steps.
- Take the total of your gross self-employment and property income.
- Select MTD-enabled software.
- Spreadsheets alone aren’t sufficient unless they’re bridged together via compatible bridging software.
- Test out a couple of options with a month’s worth of transactions before deciding on one since almost all of them come with a free trial period.
- Keep your personal finance separate from your business finance.
- Make entries into your accounting books either weekly or monthly, not quarterly.
- Consult an accountant soon enough so you have something to analyze during the quarterly reporting period.
Though quarterly reports are not the full tax return, they should still be accurate and submitted on time. Normally, they are to be submitted within one month after each quarter comes to an end, and there is a point-based system of penalties for late submissions. Make up a straightforward schedule with your own deadline a week before the actual one, to have time to correct anything that has gone wrong with your receipts or transactions categorisation. The landlords should especially take care to separate their expenses on repairs from improvement costs, as well as keep track of each property’s income, as their taxation is different. If you have co-owned properties, decide in advance who will handle the record-keeping.
Prepare for Seasonal Variations and Unexpected Events
The income is never steady. The retailers and hospitality industry located at seaside locations like Southend and Maldon can experience peak and off seasons, while the service provider might encounter project delays during some times. You can check your sales in previous years to identify the trend and save some of the additional money earned in peak months for the off-season.
Emergency savings will enable you to deal with any equipment maintenance issues or increase in the price of supplies by suppliers or their late payment. The amount of the emergency savings will depend on your requirements as a company that has a physical presence along with employees needs more savings than freelancers.
Design a simple seasonality chart based on sales from the last two years. Identify the months that you perform best and worst in, and determine the average monthly excess during peak times and the average monthly deficit during off-peak times. This will allow you to know how much money to save when doing well so that off-peak times do not cause you any trouble. For instance, a seaside café at Southend may save money during summer so that they can cover their expenses during the winter. Off-peak times can be used for profitable but low-cost activities such as redesigning your website, reaching out to old customers, and checking your pricing policies.
Evaluate Performance Periodically
Records prove their worth when used for decision making. Keep track of a few important figures.
- Revenue helps understand whether your income has grown compared to earlier periods
- Gross profit represents the money that remains after covering direct cost of delivery of your product/services
- Operating expenses help evaluate whether your overheads have increased compared to your revenues
- Invoices outstanding will tell you how much your clients owe you
- Cash available will indicate whether you can pay your obligations
These factors provide a more accurate picture than just sales, because your revenue can increase while your profits decrease. Monthly evaluation helps assess short term changes and quarterly one helps identify overall tendencies. Set goals for yourself like reducing your overdue invoices or increasing your margins.
Keep a dashboard that fits on a single page for fast reviews. Show your five metrics alongside this month, last month, and the corresponding month of the previous year. It will be more noticeable if there is a trend towards an increase in outstanding invoices or a decrease in gross profit margin when comparing these metrics on one page than from reviewing the whole set of financial statements. Gross profit margin is calculated as gross profit divided by revenues and it should be analyzed in connection with the movements following price changes or suppliers’ costs. When using accounting software, most packages provide a profit and loss statement as well as an aged debtors report just in a few mouse clicks.
Planning for Growth
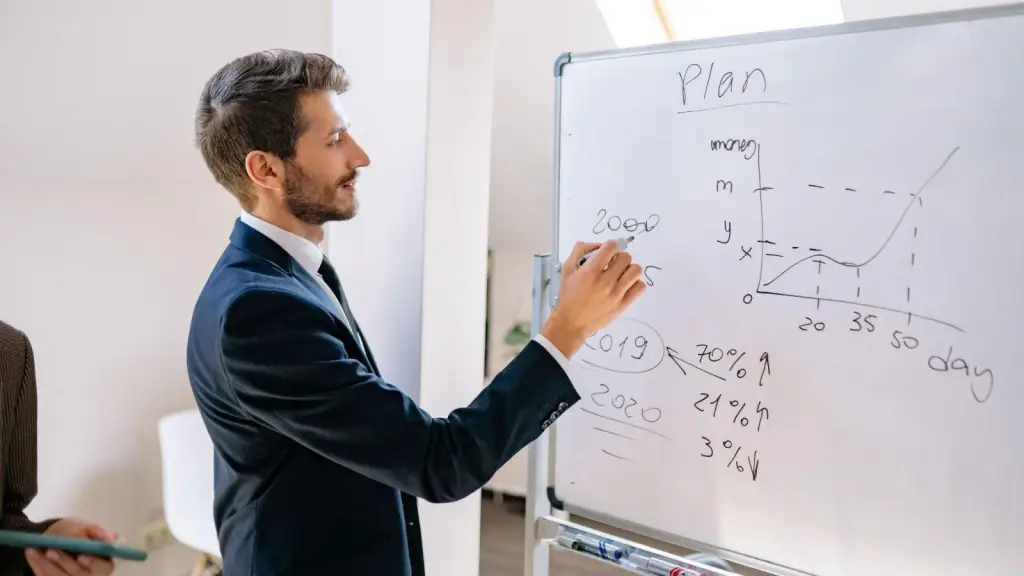
After everything is settled, think about expanding the business by hiring staff, investing in equipment or marketing, or having a second location. But first, figure out the cost of doing so as well as the recurring obligations that will follow. A new hire means paying salary, employer’s national insurance, pension payments and training. A new location in Essex comes with rent, utility bills and hiring staff, and it should be assured that there is sufficient demand for the same.
Think in terms of modeling a few scenarios where sales exceed expectations, stay constant or fall below expectations. Every important business decision should have a purpose behind it and be capable of delivering results.
Try something before you commit yourself completely. For example, if you are contemplating hiring more staff, start by using freelancers or part-time substitutes until you find that you really do have a demand to meet. If you are contemplating adding a service to your range, test the market on your existing clients, and see what happens before you spend money on new equipment. Figure out your break-even point on any significant capital investment, meaning how much additional revenue you will require every month merely to cover the new expenses. If this seems to be impossible to achieve with your present client list, then scale back your plans.
Knowing When to Use a Professional’s Help
While doing everything yourself may work fine in the initial days, as more transactions take place and there are many duties to handle, the role of an accountant becomes necessary, and he/she will ease your administrative burden and increase your supervision. Such assistance can be in the form of bookkeeping, accounts, tax, payroll, budgeting and performance appraisal.
A sole trader may require help primarily in the form of bookkeeping and Self Assessment whereas an employee-based limited company may require assistance in the form of company accounts, Corporation Tax, payroll and regular accounting. The knowledge of the locality is essential. The accountant in Essex is familiar with the range of tradesmen, seasonal business, landlords and expanding limited companies in the area.
Before choosing someone, know the range of services offered, cost involved and frequency of reports to be generated.
It is advisable to get an accountant at certain crucial stages. Such crucial stages include getting VAT registered, employing your first employee, incorporating your sole trade business, acquiring a property or going past the MTD threshold. It is cheaper to obtain professional advice when you are in the planning stages as compared to obtaining help once there is a problem. In preparation for the first meeting, it would be prudent to come with the previous year’s account statement or bank statement, together with a list of questions and your future plans. Find out if the accountant uses cloud software that works with yours.
Conclusion
In order to manage finances well, you need to be on top of cash flow, budgeting, record keeping, expenses and tax. The coming changes from Making Tax Digital mean the sooner you get yourself some good routines in place, the easier it’ll be to adapt.
It’s a quick monthly routine for the basics:
- Check your bank statement to ensure all your transactions are correctly categorised.
- Collect unpaid invoices which are more than 14 days old.
- Forecast your cash flow for the next three months.
- Transfer the money set aside for tax into your savings account.
- Compare actual expenditure with your budget.
As your business develops, assess your requirements and seek professional help where appropriate.
Note: This article provides general information only and does not constitute tax advice. Regulations and limits can be subject to change, so consult the most recent information at gov.uk or visit a professional tax adviser, such as arb.accountants.